- KPI – June 2026: The Brief
- KPI – June 2026: State of Business – Automotive Industry
- KPI – June 2026: State of the Economy
- KPI – June 2026: Consumer Trends
- KPI – June 2026: Recent Vehicle Recalls
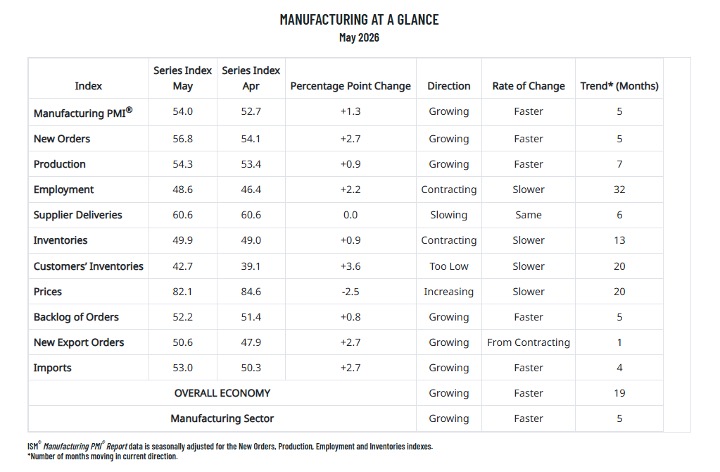
Economic activity in the manufacturing sector expanded in May for the fifth consecutive month, according to the nation’s supply executives in the latest ISM Manufacturing PMI Report. The Manufacturing PMI registered 54% in May, 1.3 percentage points higher than in April and its highest reading since May 2022 (55.9%). The overall economy continued in expansion for the 19th month in a row.
“In May, U.S. manufacturing activity remained in expansion territory — growing at a faster pace compared to the month before. Of the five subindexes that make up the PMI, the New Orders index indicated faster growth compared to the previous month, the Supplier Deliveries index stayed the same, the Production Index grew at a faster rate and the Employment and Inventories indexes remained in contraction — though both improved,” says Susan Spence, MBA, chair of the Institute for Supply Management (ISM) Manufacturing Business Survey Committee.
Data shows only 2% of the sector’s gross domestic product (GDP) contracted in May, compared to 19% in April. Likewise, the percentage of manufacturing GDP in strong contraction (defined as a composite PMI of 45% or lower) also registered 2%, the same as in April.
“The share of sector GDP with a PMI at or below 45% is a good metric to gauge overall manufacturing weakness. All of the six largest manufacturing industries expanded in May, in the following order: Computer & Electronic Products, Machinery, Transportation Equipment, Petroleum & Coal Products, Chemical Products, and Food, Beverage & Tobacco Products. In May, all indexes headed in a direction that suggests sustained growth,” Spence says.
Important Takeaways, Courtesy of the Manufacturing ISM Report On Business:
- Three of four demand indicators (the New Orders, Backlog of Orders and New Export Orders indexes) expanded. The Customers’ Inventories Index remains in “too low” territory, contracting at a slower rate. A “too low” status for the Customers’ Inventories Index is usually considered positive for future production.
- Regarding output, the Production Index expanded for the seventh month in a row, while the Employment Index increased by 2.2 percentage points but remained in contraction. Among panelists, 50% indicated that managing headcounts remains the norm at their companies, while 50% are hiring.
- Inputs — defined as supplier deliveries, inventories, prices and imports — were mostly improved month over month. With the same reading as in April, the Supplier Deliveries Index stayed at its highest level since May 2022 (65.7%). The Inventories Index contracted at a slower rate, the Prices Index declined by 2.5 percentage points and the Imports Index grew at a faster rate.
What Respondents Are Saying:
- “Impact of Iran conflict starting to directly and negatively impact cost of supply chain. Oil and related commodities are escalating in price.” [Transportation Equipment]
- “The Middle East conflict is triggering shipment delays and uncertainties. Elevated gas prices and inflation will surely impact our purchases. However, over the last quarter, we’ve seen increased demand that was unexpected.” [Machinery]
- “As with all companies, we have felt the effects of fuel-related inflation and general market uncertainty due to overall economic variability and geopolitical events that have impacted such markets as construction, automotive and agriculture, as well as the general industrial sector.” [Chemical Products]
- “Continuing trends of 15% sales increase in April, cost increases on a majority of raw materials, and fuel charges on many inbound and outbound deliveries. We remain cautiously optimistic that if global economic factors stabilize and the Iran conflict ends, we can continue with increased sales and maintain acceptable margins.” [Chemical Products]
- “Cost of diesel is having huge impacts on our profitability. Confusion abounds around tariff refunds. We purchase many imported goods, but in most cases are not the importer of record, so it is currently unclear to what we may be entitled.” [Food, Beverage & Tobacco Products]
- “Prices continue to rise for many products — some due to increase in data center creation for electronic components, others as a result of the Iran war and reductions in availability of oil/petroleum.” [Computer & Electronic Products]
- “Supply constraints continue to propagate and are a key headwind to supporting increased aerospace and defense demand. Semiconductors, critical minerals and certain types of raw materials are illustrative examples of sales plans at risk. Corporate risk mitigation actions are underway to secure supply in the midst of constraints.” [Transportation Equipment]
- “The current atmosphere is one of extreme uncertainty and concern for the future in terms of both price stability and longer-term supply continuity related to the Iran conflict and Strait of Hormuz closure. We have a lot of negotiations in process related to requested price increases, some related to oil prices and some still fallout from the 2025 tariff/geopolitical climate.” [Miscellaneous Manufacturing]
- “Continued dynamic random-access memory (DRAM) volatility, increased gas prices and tariffs are causing long lead constraints and price hikes that customers are not willing to bear. Panic is starting within our industry.” [Electrical Equipment, Appliances & Components]
- “Business appears to be weakening — uncertainty surrounding the Iran war, rising energy prices and customers unwilling to commit to expenditures beyond a very short term.” [Fabricated Metal Products]