- KPI – May 2026: The Brief
- KPI – May 2026: State of Business – Automotive Industry
- KPI – May 2026: State of the Economy
- KPI – May 2026: Consumer Trends
- KPI – May 2026: Recent Vehicle Recalls
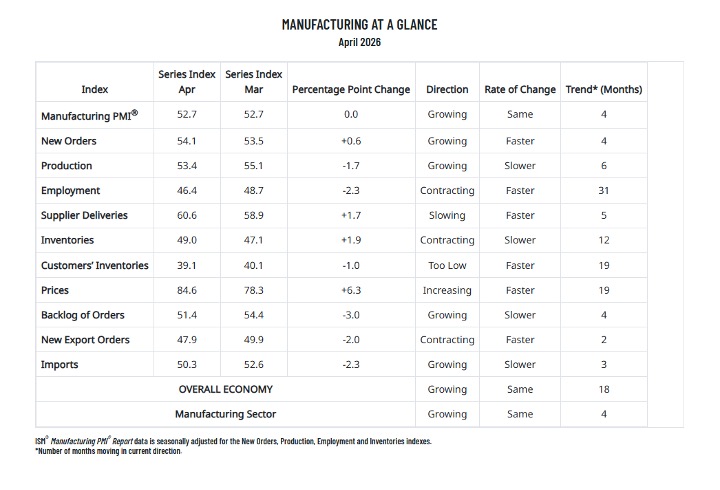
Economic activity in the manufacturing sector expanded in April for the fourth consecutive month, according to the nation’s supply executives in the latest ISM Manufacturing PMI Report. The Manufacturing PMI registered 52.7% in April, the same reading as March. The overall economy continued to expand for the 18th month in a row.
“In April, U.S. manufacturing activity remained in expansion territory, growing at the same pace as the month before. Of the five subindexes that make up the PMI, the New Orders and Supplier Deliveries indexes indicated faster growth compared to the previous month; the Production Index grew at a slower rate; and the Employment and Inventories indexes remained in contraction,” says Susan Spence, MBA, chair of the Institute for Supply Management (ISM) Manufacturing Business Survey Committee.
Data shows 19% of the sector’s gross domestic product (GDP) contracted in April, compared to 16% a month prior. In addition, the percentage of manufacturing GDP in strong contraction decreased to 2%, compared to 4% in March.
“The share of sector GDP with a PMI at or below 45% is a good metric to gauge overall manufacturing weakness. Of the six largest manufacturing industries, four (Transportation Equipment, Machinery, Computer & Electronic Products and Chemical Products) expanded in April,” Spence says.
Important Takeaways, Courtesy of the Manufacturing ISM Report On Business
- Two of four demand indicators (the New Orders and Backlog of Orders indexes) remain in expansion, although the Backlog of Orders Index dropped 3 percentage points compared to March. The New Export Orders Index remained in contraction with a 2-percentage-point decrease and the Customers’ Inventories Index remains in “too low” territory, contracting at a slightly faster rate. A “too low” status for the Customers’ Inventories Index is usually considered positive for future production.
- Regarding output, the Production Index is in expansion for the sixth month in a row (although it lost ground compared to March). The Employment Index decreased by 2.3 percentage points and remains in contraction. Among panelists, 60% indicated that managing headcounts remains the norm at their companies as opposed to hiring. Of those managing headcounts, 34% are using layoffs, and 43% are using attrition or not backfilling positions.
- Inputs—defined as supplier deliveries, inventories, prices and imports—posted another month of mixed results. The Supplier Deliveries Index indicated increasingly slowing deliveries, the Inventories Index contracted at a slower rate, and the Prices Index vaulted again—up to 84.6% from 78.3% in March. The Imports Index lost 2.3 percentage points for a reading of 50.3% compared to 52.6% in March.
What Respondents Are Saying
- “Demand for manufactured goods is trending higher versus last year; however, geopolitical uncertainty and rising oil and diesel prices continue to weigh on demand. Many customers are exercising caution and remain in a wait-and-watch mode.” [Transportation Equipment]
- “Continued tariffs on products utilized in our product lines are being monitored by the business, with the business working to mitigate or limit tariff risk. Geopolitical risk, especially in the Middle East, as it pertains to commodity and energy markets, remains a concern and is being monitored by the business. Supply chain risk concerns pertaining to increased cost and transit time for rerouted shipments due to conflict in the Red Sea, Strait of Hormuz and Suez Canal. These conditions are being monitored by the business, and rerouting measures have been implemented where possible.” [Transportation Equipment]
- “Continuing fluctuation in U.S. tariffs as well as market constraints for certain materials are affecting our current business. U.S. support of AI-related industry is also in flux, which is causing some customer and investment hesitancy.” [Computer & Electronic Products]
- “All products tied to crude, polyethylene resin or energy (liquefied natural gas) have seen multiple increase spikes tied to the Iran crisis and market supply inflation.” [Chemical Products]
- “Revenues are very strong. However, price increases are similar to a few years ago with the supply chain crisis. All imports from China are up 15%-25%, which is impossible for us to absorb or to fully pass along. Our suppliers in China are telling us that oil is at an all-time high, which is putting huge challenges on their cost structures.” [Chemical Products]
- “General uncertainty over the total impact of the U.S.-Iran war. Have not yet started to see the full impact of fuel increases but are aware they are coming.” [Machinery]
- “Business levels have been decent this year, in line with the same period last year and improved from the second half of 2025. However, higher cost pressures are impacting margins.” [Fabricated Metal Products]
- “Commodity markets remain mixed, with pockets of easing offset by ongoing volatility. Dairy and some soft commodities have cooled, while oils and grain-related inputs remain elevated given biofuel demand and feed costs. Pricing is still sensitive to policy changes, weather and global trade dynamics.” [Food, Beverage & Tobacco Products]
- “Our business remains strong and stable, but there are a lot of concerns in the geopolitical arena. If the Iran conflict persists, the impact on market pricing and supply continuity could be extreme. Electronics component market remains very volatile (pricing and continuity) based on AI.” [Miscellaneous Manufacturing]