- KPI – May 2026: The Brief
- KPI – May 2026: State of Manufacturing
- KPI – May 2026: State of the Economy
- KPI – May 2026: Consumer Trends
- KPI – May 2026: Recent Vehicle Recalls
Global Light Vehicle Sales
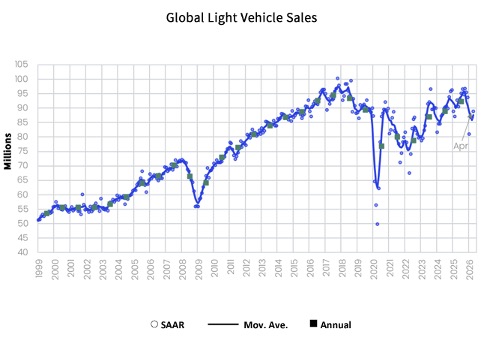
In April, the global light vehicle (LV) selling rate improved to 89 million units per year but remained nearly 7% below the 92 million units per year recorded a year earlier. Overall, sales declined 3.4% year-over-year.
Global light vehicle sales continued to trail 2025’s pace, as a pronounced slowdown in China is affecting overall growth. Policy support has been slower and less impactful in reaching Chinese consumers this year—most notably the delayed and uneven rollout of trade-in incentives—while price normalization and broader economic headwinds are tempering demand as well.
Meanwhile, sales in the U.S. and Western Europe remain resilient, despite a deteriorating global economic backdrop. U.S. volumes outperformed expectations, even against a tough April comparison that was boosted last year by tariff-related pull-forward demand. Western Europe continues to benefit from the increasing availability of lower-priced models and supportive EV policy.
“Our forecast for total global sales in 2026 has been revised down to 91.7 million units, compared to an outlook of 92.6 million units a month ago. The downgrade is symbolically significant, since it means that total global volumes are now expected to fall year-over-year, though the decline would be a modest 0.4%. The conflict in the Middle East is one key factor behind the downward revision, as the downstream consequences of the war on energy prices, GDP growth and consumer confidence start to influence light-vehicle sales forecasts. This is true even for regions with few direct links to the Middle East from a supply chain perspective, such as North America. However, the slow implementation of the new subsidy scheme in China and the cooling of the price war in that market are also notable considerations,” says David Oakley, manager of Americas vehicle sales forecasts at GlobalData.
U.S. New Vehicle Market
Total new vehicle sales for May 2026, including retail and non-retail transactions, are projected to reach 1,490,900—a 5.8% year-over-year increase, according to a joint forecast from J.D. Power and GlobalData. Experts warn it is important to put the data in perspective, with annual comparisons being clouded by what happened a year ago when consumers reacted to the perceived risk of higher prices from vehicle tariffs.
“Sales in March and April of last year were inflated as consumers rushed to showrooms and pulled ahead their purchases. But by May, however, the pull-ahead had turned into payback, with an estimated 63,000 sales pulled out of May into the preceding months. This payback effect makes for a flattering year-over-year comparison, but in no way diminishes the impressive sales pace achieved. Retail volume is on pace to expand 6% to 1,231,900 units, even as buyers continue to navigate elevated payments and persistent affordability headwinds,” says Thomas King, president of the data and analytics division at J.D. Power.

Key Takeaways, Courtesy of J.D. Power
- Retail buyers are on pace to spend $53.8 billion on new vehicles, up $3.5 billion from a year ago.
- Trucks/SUVs account for 81.9% of new vehicle retail sales, up 1.8 percentage points year-over-year.
- Lease penetration continues to recover from the post-pandemic drought, with 22.6% of buyers opting to lease in May. This is up 0.3 percentage points from a year ago and provides OEMs with a useful tool to manage monthly payment challenges.
- The average new vehicle retail transaction price is expected to reach $45,462, up $649 from a year ago.
- Average incentive spending per vehicle is trending toward $3,297, a 20.7% year-over-year increase.
- Average monthly finance payments are on pace to be $748, up $21 from May 2024. The average interest rate for new-vehicle loans is expected to be 6.93%, down 0.10 percentage point from a year ago.
- Total retailer profit per unit—which includes vehicle gross plus finance and insurance income—is expected to be $2,502, up $98 from May 2024 but down $29 from April. Total aggregate retailer profit from new-vehicle sales for this month is projected to be $3 billion, up 9.8% from a year ago.
- Fleet sales are expected to total 254,069 units in May, down 7% from May 2024. Fleet volume is expected to account for 17.1% of total light-vehicle sales, down 1.2 percentage points from a year ago.
“Looking forward, the industry sales pace faces challenges on a number of fronts. For certain, sales pulled forward into March, April and May will become a meaningful headwind for the balance of the year,” King says. “Less certain are the challenges related to tariffs. The effect of tariffs on the general economy remains ambiguous but, directionally, pose a meaningful risk to vehicle demand.”
U.S. Used Market
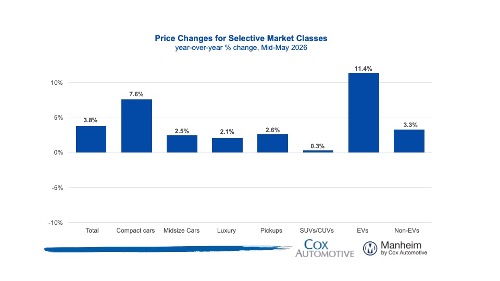
Manheim Used Vehicle Value Index (MUVVI) increased to 213.1, reflecting a 0.5% increase in wholesale used-vehicle prices (adjusted for mix, mileage and seasonality) in the first 15 days of May compared to April, and a 3.8% increase compared to May 2025. Seasonally adjusted wholesale values typically increase by about 0.9% on average over the full month.
“Wholesale used-vehicle prices moved a bit higher in early May compared to the end of April. The Manheim Used Vehicle Value Index is holding roughly 4% higher than this time last year. The spring bounce buoyed the market, as a stronger tax refund season drove dealer demand earlier in the year. While the index is now down from its near-term peak in March, depreciation trends have remained muted versus normal seasonal trends,” says Jeremy Robb, chief economist at Cox Automotive.
In addition, he says nationwide gas prices have been holding at $4.50 or higher since May 6. Inflation trends are creeping up and may begin to eat into consumer spending appetites as we move into early summer.
“In the wholesale markets, we continue to see the impact of affordability driving demand, as some of the strongest performing segments are lower priced vehicles in the 8+ year-old range. More demand and higher values in older units tends to lift the Manheim Index overall,” Robb says.
Moreover, EV prices continue to rise faster and hold higher than non-EVs. Three-year-old EV prices have outpaced non-EVs for six weeks in a row and are 11% higher than where they started the year.
“The longer gas prices remain elevated, the more we expect consumers to turn to fuel-efficient vehicles,” he says. “As EV lease maturities continue to increase throughout the summer, it will be critical to follow EV price trends—especially if the Middle East conflict remains unresolved.”
Click here to view results by segment.