- KPI – March 2026: The Brief
- KPI – March 2026: State of Business – Automotive Industry
- KPI – March 2026: State of the Economy
- KPI – March 2026: Consumer Trends
- KPI – March 2026: Recent Vehicle Recalls
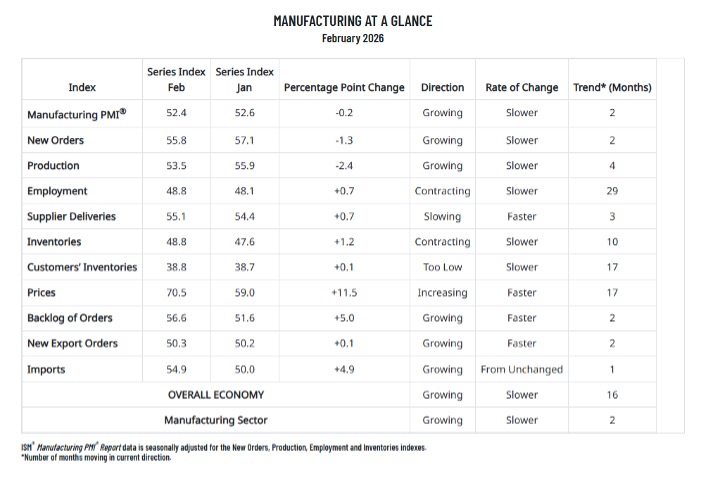
Economic activity in the manufacturing sector expanded for the second straight month. The Manufacturing PMI registered 52.4% in February, a 0.2-percentage point decrease compared to the reading of 52.6 in January. The overall economy continued to expand for the 16th month.
“In February, U.S. manufacturing activity remained in expansion territory, although growing at a slower pace than the month before. Of the five sub-indexes that make up the PMI, two (New Orders and Production) indicated slower growth compared to the previous month, while the Employment and Inventories indexes remained in contraction,” says Susan Spence, MBA, chair of the Institute for Supply Management (ISM) Manufacturing Business Survey Committee.
Data shows 21% of the sector’s gross domestic product (GDP) contracted in February, compared to 20% in January, and the percentage of manufacturing GDP in strong contraction—defined as a composite PMI of 45% or lower—decreased to 1%, compared to 12% in January.
“The share of sector GDP with a PMI at or below 45% is a good metric to gauge overall manufacturing weakness. Of the six largest manufacturing industries, four (Chemical Products, Machinery, Transportation Equipment and Computer & Electronic Products) expanded in February,” Spence says.
Important Takeaways, Courtesy of the Manufacturing ISM Report On Business:
- Three demand indicators (the New Orders, Backlog of Orders and New Export Orders indexes) expanded. The Customers’ Inventories Index remains in “too low” territory, contracting at a slightly slower rate. A “too low” status for the Customers’ Inventories Index is usually considered positive for future production.
- Regarding output, the Production Index is in expansion for the fourth month in a row. The Employment Index, though still in contraction, improved by 0.7-percentage points. However, 45% of panelists still indicate that managing headcounts is the norm at their companies as opposed to hiring.
- Inputs—defined as supplier deliveries, inventories, prices and imports—all increased compared to the previous month’s reading. The Supplier Deliveries Index indicated slower deliveries, while the Inventories Index contracted at a slower pace and the Prices Index took a huge leap from 59% in January to 70.5% in February.
What Respondents Are Saying:
- “Today, American-produced commodities like steel and aluminum are the highest priced in the world, by far. Hence, the Section 232 tariff policy is having the exact opposite effect of their intention on an American manufacturer like us: It is raising prices, while lowering demand and profitability.” [Transportation Equipment]
- “Economic activity seems to be also challenging for this year. Some recovery in certain sectors in the economy, but still lot of cost pressures and soft demand. Cost discipline is the priority.” [Chemical Products]
- “January sales continued to provide positive indications for growth opportunities. Data center, health care, food and beverages remain positive growth areas. We continue to receive price increase notifications from suppliers based on unsupported tariff claims and are expanding corporate staff to support sales growth.” [Chemical Products]
- “South American instability has begun to be a factor for our suppliers and inventory management.” [Petroleum & Coal Products]
- “Pricing for outside purchases has stabilized. We are spending significant effort to work with our supply base to mitigate tariff impacts. Backlog is at a healthy level.” [Miscellaneous Manufacturing]
- “Overall orders and the supply footprint are improving. As we review customer demand, we are also taking several categories of established materials and supplies out to RFP for review and cost improvements—in particular, printed circuit assemblies, plastics, sheet metal assemblies and motorized assemblies. This will help ease the burden of tariff and customer impacts as we broaden our supplier base to a more regional footprint.” [Computer & Electronic Products]
- “Continue to be impacted by tariffs. Seeing metals prices rise too. Business is steady, but domestic growth is slower than expected.” [Computer & Electronic Products]
- “Business was slow in January. Many orders pulled into end of 2025 to meet revenue goals. Order book is strong going forward.” [Electrical Equipment, Appliances & Components]
- “Tariff policy changes affect total acquisition costs and purchasing source decisions. So far this year, tariff instability still exists. Due to the tariffs, most raw materials used in manufacturing, such as steel and wire, need to be sourced domestically, and the cost keeps going up.” [Machinery]
- “Business is improving by the week. Backlog is growing, and new opportunities are everywhere. Monthly shipments are still lower than planned, but improving. Over the past five years, we spent thousands trying to attract new employees and had almost zero responses. In the last six months, however, we’ve been able to hire experienced engineers, computer numerical control (CNC) operators and young people wanting to become CNC machinists.” [Fabricated Metal Products]