- KPI – October 2026: The Brief
- KPI – October 2026: State of Business – Automotive Industry
- KPI – October 2026: State of the Economy
- KPI – October 2026: Consumer Trends
- KPI – October 2026: Recent Vehicle Recalls
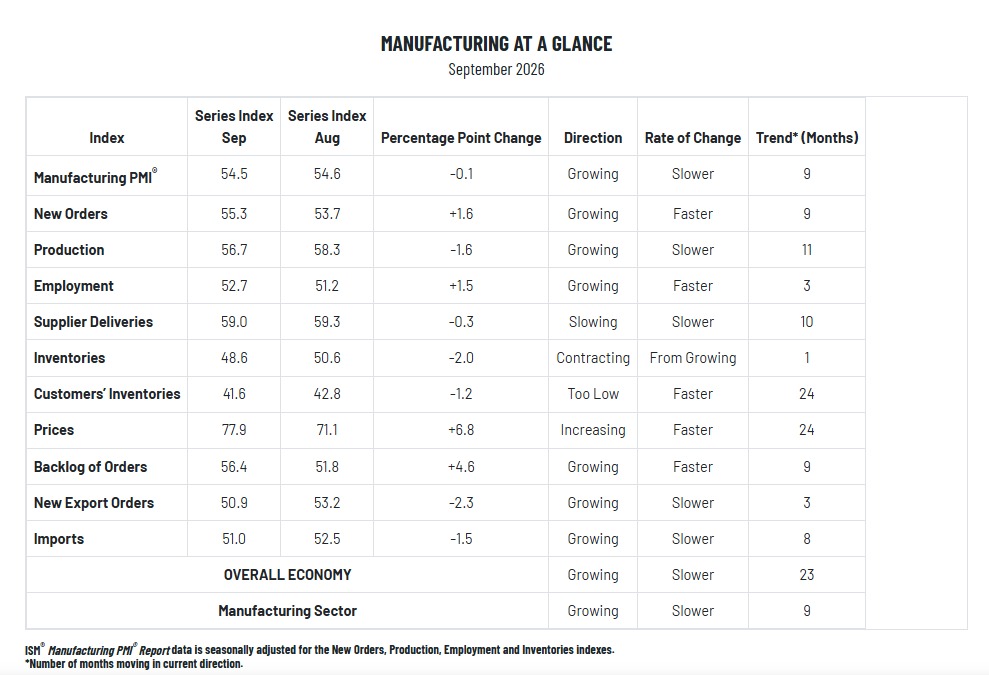
Economic activity in the manufacturing sector expanded for the ninth consecutive month during September, according to the nation’s supply executives in the latest ISM Manufacturing PMI Report. The Manufacturing PMI registered 54.5%, 0.1 percentage point below the August figure of 54.6%. The overall economy continued in expansion for the 23rd month in a row.
“U.S. manufacturing activity remained in expansion territory. Of the five sub-indexes that make up the PMI, only New Orders and Employment grew faster than the previous month. In September, 40% of the comments were positive and 60% negative, with a 1-to-1.6 ratio of positive to negative sentiment. Among negative comments, pricing volatility was mentioned in 46%, tariffs 34%, the Iran war 30% and increasing lead times 21%. Most comments mentioned multiple factors,” says Susan Spence, chair of the Institute for Supply Management (ISM) Manufacturing Business Survey Committee.
Data shows 2% of the sector’s gross domestic product (GDP) contracted in September, compared to 22% in August. In addition, 2% of manufacturing GDP was in strong contraction (defined as a composite PMI of 45% or lower), the same as in August.
“The share of sector GDP with a PMI at or below 45% is a good metric to gauge overall manufacturing weakness. Of the six largest manufacturing industries, five (Computer & Electronic Products; Food, Beverage & Tobacco Products; Transportation Equipment; Machinery; and Chemical Products) expanded in September,” Spence says.
Important Takeaways, Courtesy of the Manufacturing ISM Report On Business:
- Three of four demand indicators (the New Orders, Backlog of Orders and New Export Orders indexes) remained in expansion, while the Customers’ Inventories Index remained in “too low” territory, contracting at a faster rate. A “too low” status for the Customers’ Inventories Index is usually considered positive for future production.
- Regarding output, the Production Index expanded for the 11th month in a row, with the positive-to-negative comment ratio dropping again in September. The Employment Index remained in expansion and gained 1.5 percentage points. The positive-to-negative comments ratio on Employment was 1.5-to-1 in September.
- Inputs—defined as supplier deliveries, inventories, prices and imports—were mixed, with the Supplier Deliveries Index decreasing 0.3 percentage points, the Inventories Index declining another 2 percentage points and returning to contraction, and the Prices Index increasing 6.8 percentage points, returning to its level at the start of the Iran war. The Imports Index lost 1.5 percentage points, from 52.5% in August to 51% in September.
What Respondents Are Saying:
- “Better performance was driven primarily by temporary market effects, including (1) geopolitical uncertainties, (2) customers bringing forward purchases, (3) delayed raw material price increases and (4) reduced competitor capacity. However, these factors do not signal sustained recovery: Structural challenges facing the chemical industry remain, including overcapacity, persistent pricing pressures and protectionist trade policies.” [Chemical Products]
- “Supply chain performance has improved compared to prior years, with lead times largely normalized. Cost pressures persist in select raw materials, transportation and labor categories, requiring continued focus on supplier management and cost control. We remain cautiously optimistic about business conditions over the next several quarters.” [Chemical Products]
- “The U.S. tariff schedule is providing challenges. Finding alternate sources of supply outside of China, local pushback on data centers in the U.S. and continuing material/component shortages are affecting business.” [Computer & Electronic Products]
- “Manufacturing activity remains stable, with a continued focus on cost optimization, supplier negotiations and supply base consolidation. We are actively evaluating alternative sources in several categories to improve supply resilience and reduce costs. While material availability has generally improved compared to prior periods, qualification requirements and supplier capacity constraints continue to influence sourcing decisions for certain critical materials and components. Capital and operational spending remain focused on productivity, efficiency and transformation initiatives.” [Computer & Electronic Products]
- “Orders have doubled yet again, and delivery times have also doubled, in the semiconductor, electronics and government sectors, with remaining sectors flat to down. Coupled with supply chain lead times and pricing pressures, the factory backlog has nearly doubled. Canada tariffs have impacted cross-border costs and left our supply chain team scrambling—those supply chains took years to develop and nurture—hurting the very lead times government buyers are concerned about.” [Machinery]
- “Order levels remain strong and elevated. We have orders through year-end at above forecast levels. Our biggest challenge continues to be a severe shortage of workers, limiting our production output to meet demand. The second challenge is general availability of steel. The market is getting worse and more production delays are expected as we gap out of needed material.” [Fabricated Metal Products]
- “Raw metals continue to be challenging, especially with the uncertain nature of tariffs being on and off again. New tariffs against Canada have drastically increased costs for capital expenses, as well as assemblies.” [Electrical Equipment, Appliances & Components]
- “Fuel costs are still affecting transportation costs and the overall cost of goods. Beef costs remain high, with no relief in sight.” [Food, Beverage & Tobacco Products]
- “Higher interest rates slow down the growth of new construction projects. We also have to face up to the higher cost of components from overseas due to tariffs and freight rates. Due to booming demand of AI and data centers, domestic steel capacity has been stretched and pushed. Higher steel costs each month increase our raw-material and finished-goods costs.” [Machinery]
- “Every month, we are faced with new headwinds created by this administration. This month, it is the trade war with Canada, which every day is getting worse—causing prices to go up and uncertainty that creates massive disruption. Buying continues to get pushed out indefinitely as customers don’t want to spend on capital expenditures until there is more certainty of costs and demand. The only thing that is predictable is the chaos that is created by these trade policies.” [Transportation Equipment]