
- KPI – July 2026: The Brief
- KPI – July 2026: State of Business – Automotive Industry
- KPI – July 2026: State of the Economy
- KPI – July 2026: Recent Vehicle Recalls
Below is a synopsis of consumer sentiment, confidence, demand and income/spending trends.
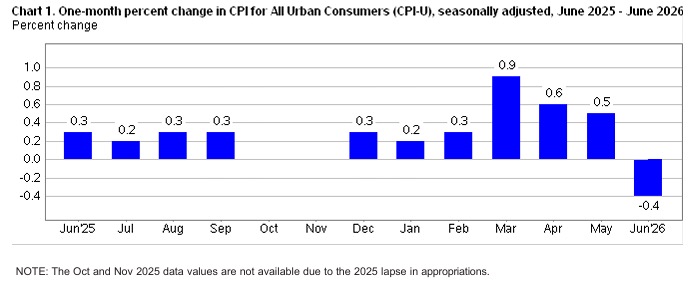
In June, the Consumer Price Index for All Urban Consumers (CPI-U) decreased 0.4% on a seasonally-adjusted basis after rising 0.5% in May, according to the U.S. Bureau of Labor Statistics. The decline in the all-items index was the largest one-month decrease since April 2020, when it fell 0.8%. Over the last 12 months, the all-items index increased 3.5% before seasonal adjustment.
Most recently, the energy index dropped 5.7% after rising 3.9% in May, 3.8% in April and 10.9% in March. It was the largest contributor to the monthly all-items decrease, more than offsetting increases in other indexes including those for shelter and food. The index for food increased 0.2% month-over-month, as did the index for food-at-home and the index for food-away-from-home.
In June, the index for all-items-less-food-and-energy was unchanged. Indexes that decreased over the month include motor vehicle insurance, communication, apparel, medical care and used cars and trucks, while recreation, household furnishings and operations, as well as personal care, were among the major indexes to increase.
The all-items index rose 3.5% year-over-year on the heels of a 4.2% increase last month. The all-items-less-food-and-energy index inched up 2.6% year-over-year after rising 2.9% during May. The energy index increased 15.7% year-over-year, while the food index increased 3%.

Sentiment
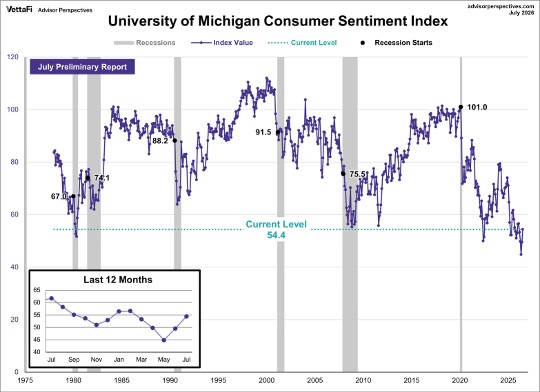
The University of Michigan Survey of Consumers—a survey consisting of approximately 50 core questions covering consumers’ assessments of their personal financial situation, buying attitudes and overall economic conditions—registered 49.5 in June and posted a preliminary reading of 54.4 in July.
“With the second straight month of 10% jumps, consumer sentiment climbed to its highest reading since February of this year on the basis of easing price pressures at the pump in recent weeks. All five index components improved, led by significant 20% increases in buying conditions for durables, as well as year-ahead business conditions,” says Joanne Hsu, director at Survey of Consumers.
Data shows the rise in sentiment was “pervasive across the population,” including age, income, wealth and political party. Hsu notes particularly strong increases among consumers without a bachelor’s degree.
“However, with prices remaining frustratingly high, consumers are hardly ebullient about the economy; sentiment is down 12% from a year ago. Thus, sentiment’s upward momentum may prove difficult to sustain if recent declines in gas prices continue to reverse course,” she says.

Key Takeaways, Courtesy of Survey of Consumers:
- Year-ahead inflation expectations ticked down from 4.6% in June to a still-elevated 4.2% this month. The current reading substantially exceeds the 3.4% seen in February before the Iran conflict began, along with all 2024 readings.
- Long-run inflation expectations held steady from last month at 3.3%, remaining a bit higher than the 2.8% to 3.2% range seen in 2024.

Confidence
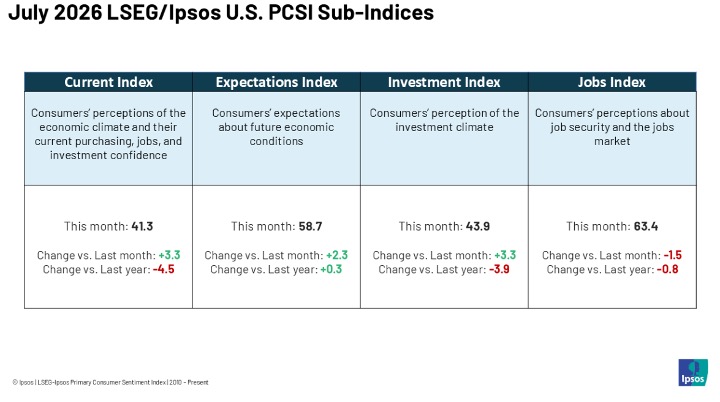
In June, the Conference Board Consumer Confidence Index edged up to 91.2 (1985=100) from a downwardly revised 90.6 in May. The Present Situation Index—based on consumers’ assessment of current business and labor market conditions—fell by three points to 116.4. The Expectations Index—based on consumers’ short-term outlook for income, business and labor market conditions—rose by three points to 74.4.
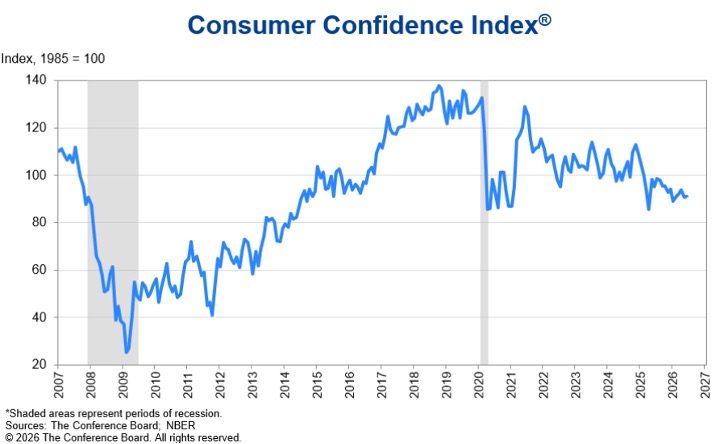

“Consumer confidence inched up in June as falling oil prices in recent weeks provided some relief to consumer inflation fears,” says Dana M. Peterson, chief economist at The Conference Board. “Consumer appraisals of current business conditions were slightly more positive compared to last month. However, perceptions of the current labor market softened measurably as the percentage of consumers saying jobs were ‘hard to get’ rose to 22.5%, the highest level since January 2021 (22.8%). Moreover, consumers anticipate little change in the labor market six months from now. This was offset by improving expectations for business conditions and incomes.”
Confidence for consumers under age 35 remained the highest, but confidence for all age groups trended downward on a six-month moving average basis. On a six-month moving average basis, confidence was mixed or little changed across all income categories. Confidence fell the most among the Silent Generation but was stable or lower for others on a six-month moving average basis. By political affiliation, confidence among Independents and Democrats rose, while Republicans were somewhat less positive on a month-over-month basis.
Key Takeaways, Courtesy of The Conference Board:
- Perceptions of current employment conditions declined, with the labor market differential—the share of consumers saying jobs are “plentiful” minus the share saying jobs are “hard to get”—declining by 2.6 ppts to just +2.4%. Notably, the percentage of consumers saying jobs are “hard to get” rose to 22.5%, a five-and-a-half-year high.
- Consumers’ net views of their Family’s Current Financial Situation deteriorated for a third month, with virtually the same portion saying conditions are “Good” versus “Bad.” However, consumer’s views of their Family’s Future Financial Situation were more optimistic, reviving the levels since the beginning of the year.
- The share of consumers who said a U.S. recession over the next 12 months is “somewhat likely” rose, but overall recession expectations remain low, with those saying recession is “not likely” declining.
- Consumers’ average and median 12-month inflation expectations were less elevated. While down somewhat from May (62.4%), most consumers (61.5%) still expected higher interest rates over the next 12 months.
- Consumers’ plans to buy big-ticket items over the next six months improved slightly, shifting from “no” to “maybe”, while the proportion saying “yes” picked up modestly. Buying plans for autos continued rising on a six-month moving average basis. Homebuying expectations also rose on a six-month rolling basis. Consumers planning purchases six months ahead continued to rank furniture followed by smartphones as the most desired items, but expectations for both categories moderated further in June.
- Consumers planning more spending on services over the next six months shifted from “no” to “maybe” in June, but future spending plans on individual services were mixed. Among all service categories, restaurants/bars/take-out, streaming/internet/mobile services, as well as beauty and personal care, remained among the top three spending targets.
- Overall travel intentions within six months receded but predominantly fell for domestic travel plans, while plans for international travel rose. Nonetheless, expected spending on hotel/motel and airfare/trains for personal travel were moderately higher in the month.
“Consumers’ write-in responses on factors affecting the economy continued to skew towards pessimism in June. References to prices and oil and gas eased in frequency but remain elevated. Mentions of war, geopolitics, and conflict eased, reflecting some easing of consumer concerns about the inflationary impacts of the war in the Middle East,” Peterson says.
Consumer Income & Spending
Editor’s note: The data from the U.S. Bureau of Economic Analysis has not yet been released for July. The information below is from the June KPI report. We will update this section as soon as the data is available.
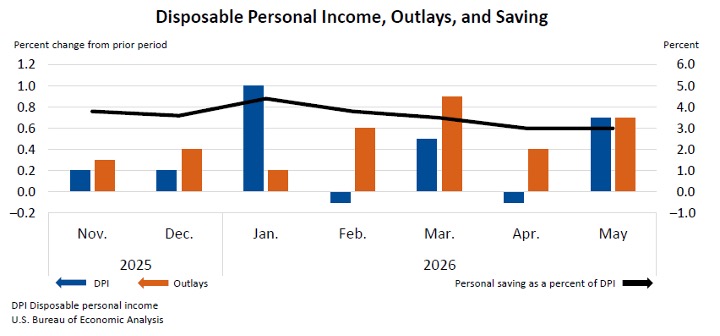
According to the U.S. Bureau of Economic Analysis (BEA), personal income, disposable income (DPI) and personal consumer expenditures (PCE) increased $181.6 billion (0.7% at a monthly rate), $164.9 billion (0.7% at a monthly rate) and $156.1 billion (0.7% at a monthly rate), respectively, in May.
Personal outlays—the sum of PCE, personal interest payments and personal current transfer payments—increased $159.9 billion. Personal saving was $704.2 billion, while the personal saving rate—personal saving as a percentage of DPI—registered 3%.

Key Takeaways, Courtesy of the U.S. Bureau of Economic Analysis:
- In May, the $156.1 billion increase in current-dollar PCE reflected increases of $94.3 billion in spending on services and $61.8 billion in spending on goods.
- Real PCE increased $43.8 billion (0.3% at a monthly rate), while the PCE price index increased 0.4%. Excluding food and energy, the PCE price index increased 0.3% since last month. The PCE price index increased 4.1% year-over-year. Excluding food and energy, it increased 3.4% from one year ago.